Cover for the building, and the income it earns.
Warehouses, retail premises, offices, industrial units and mixed-use buildings — insured for what it would actually cost to rebuild, with cover for the rent you'd lose while that work happens.
Buildings, loss of rent, fit-out, natural hazard damage and landlord liability — arranged around your property.
General information only — cover always depends on your situation. See our disclosure, privacy policy and terms of engagement.
Insurance Business Top Brokerage, five years running — awarded to the Shielded group in Australia
Three steps between you and covered
No forms in triplicate. No hold music. Just a broker who does the legwork for you.
Start a quote
Fill in the one-minute form or pick up the phone. It starts with a friendly call from an NZ broker — no paperwork, no jargon.
We do the shopping
Your broker compares cover and premiums from multiple insurers, then recommends what genuinely fits your situation.
You're covered
We arrange the policy, manage it at every renewal and fight your corner at claim time. You're now Shielded.
Broking without the old-school waffle
A young, energetic team of experts who challenge how insurance broking usually feels.
Professional advice
Qualified brokers who explain cover in plain English and recommend what fits — not what pays best.
Award-winning group
Part of the Shielded group, a multi-award-winning brokerage founded in Australia and now in New Zealand.
Renewal management
Your cover gets reviewed and re-shopped before every renewal, so it keeps up as your life or business changes.
24/7 claims
Lodge a claim any hour, any day. Then your broker manages the insurer for you, start to finish.
Cover for the rest of your world
One broker can look after all of it — just ask.
Business insurance
From cafés and trades to offices, retail and professional services — your broker arranges the cover your business actually needs, then explains it in plain English.
- Public & statutory liability
- Professional indemnity
- Business assets & interruption
- Cyber cover
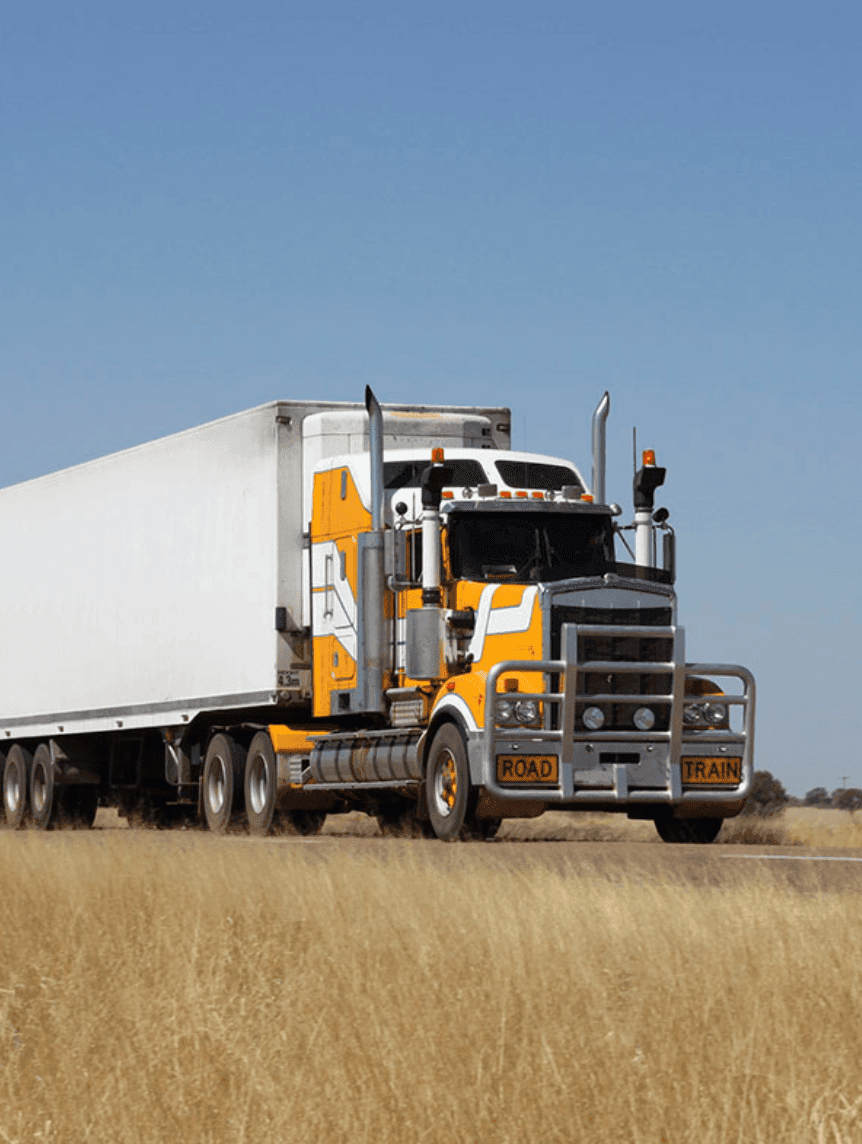
Truck & commercial vehicle
Rigids, tractor units, trailers, utes, vans and whole fleets — cover arranged by brokers who know NZ transport, whether you're line-hauling State Highway 1 or carting stock off-road.
- Trucks, trailers & fleets
- Carriers' liability
- Loss of use cover
- Utes & work vehicles
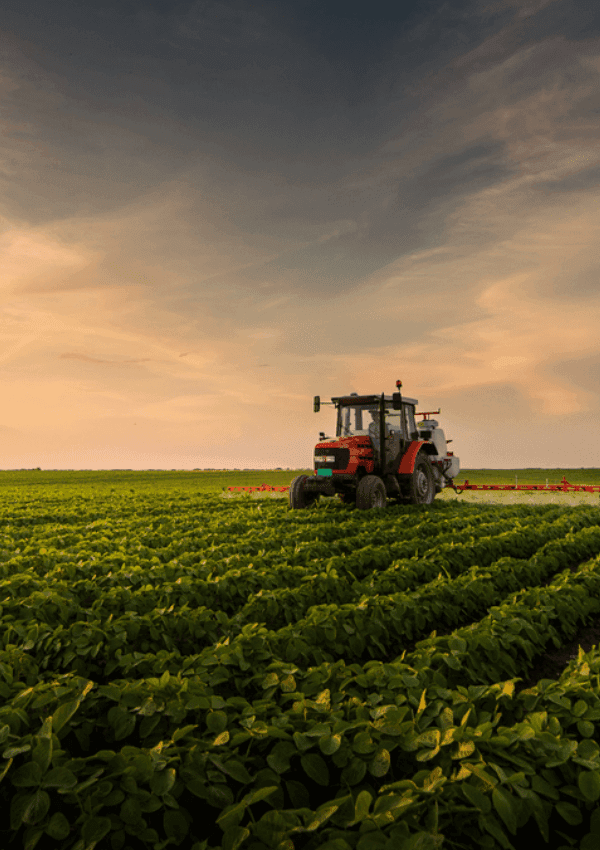
Rural & farm
Farms, lifestyle blocks, machinery, sheds and rural contracting gear — insurance arranged by brokers who understand that a farm is a home, a workplace and a business in one.
- Farm dwellings & sheds
- Tractors & machinery
- Livestock cover
- Farm liability
Home, contents & vehicle
House, contents and private vehicle insurance arranged by a broker — so you get cover that's genuinely right for you, not just the first quote a website spat out.
- House & contents
- Private vehicles
- Boats & trailers
- Landlord cover
Construction & contract works
New builds, renovations, extensions and civil works — cover for builders, contractors and tradies that looks after the job itself, the gear you turn up with, and the people around the site.
- Contract works cover
- Public liability on site
- Plant, tools & equipment
- Design & build indemnity
Commercial property questions, answered straight
No jargon, no fine-print games — just how it actually works.
How much should my commercial building be insured for?
Most commercial building policies pay up to a sum insured, so that number needs to reflect what it would cost to rebuild today — including demolition, professional fees and building to current requirements — rather than what the property would sell for. Owners commonly base it on a reinstatement valuation from a registered valuer or quantity surveyor, and revisit it every few years as construction costs move. Your broker will talk you through what your particular wording asks for.
Is my commercial building covered for earthquake and other natural hazards?
Not by the government scheme. New Zealand's natural hazard cover — run by the Natural Hazards Commission Toka Tū Ake, which many people still know as EQC — generally applies to residential homes and residential land, not commercial buildings. For a commercial property, natural hazard damage is something you arrange through your own policy, and the limits, sub-limits and excesses vary between insurers. It's worth having your broker show you exactly what yours includes.
Does my building's seismic rating affect the cover I can get?
It can. Seismic assessments are expressed as a percentage of new building standard (%NBS), and insurers may take a low rating into account when setting terms, excesses or premium — particularly for older buildings in higher-risk areas. If you've had an assessment done, or you're planning strengthening work, tell your broker early. Going to market with the engineering detail in hand usually gives us more to work with than going without it.
What does loss of rent cover actually do?
If insured damage makes your building unusable, loss of rent cover can replace the rental income you'd otherwise go without while it's repaired or rebuilt. Policies set an indemnity period — often 12, 18 or 24 months — and that's the maximum time the cover will pay for. Commercial rebuilds can run longer than owners expect once consents, engineering and contractor availability are factored in, so the length of that period is worth thinking about carefully.
Who insures the fit-out — me or my tenant?
Your lease decides it. As a general rule the landlord insures the building and any fit-out they own, while the tenant insures their own fit-out, stock, contents and liability — but leases vary, and the wording is what counts. Gaps between the two are easy to miss and tend to surface at claim time, so it pays to have your broker read the lease alongside the policy.
How is a commercial property premium worked out?
Insurers look at how the building is built, its age and location, its seismic rating, what it's used for, the sum insured and your claims history. Cover and premiums always depend on your situation — your broker gathers competitive quotes so you can compare real options for your property rather than guessing at them.
Get a quote. It’s free.
One minute now, one friendly phone call later — and the insurance legwork stops being your job.