Cover for the build, from first peg to final sign-off.
New builds, renovations, extensions and civil works — cover for builders, contractors and tradies that looks after the job itself, the gear you turn up with, and the people around the site.
Contract works, public liability, plant and tools, vehicles and design cover — arranged around the way you build.
General information only — cover always depends on your situation. See our disclosure, privacy policy and terms of engagement.
Insurance Business Top Brokerage, five years running — awarded to the Shielded group in Australia
Three steps between you and covered
No forms in triplicate. No hold music. Just a broker who does the legwork for you.
Start a quote
Fill in the one-minute form or pick up the phone. It starts with a friendly call from an NZ broker — no paperwork, no jargon.
We do the shopping
Your broker compares cover and premiums from multiple insurers, then recommends what genuinely fits your situation.
You're covered
We arrange the policy, manage it at every renewal and fight your corner at claim time. You're now Shielded.
Broking without the old-school waffle
A young, energetic team of experts who challenge how insurance broking usually feels.
Professional advice
Qualified brokers who explain cover in plain English and recommend what fits — not what pays best.
Award-winning group
Part of the Shielded group, a multi-award-winning brokerage founded in Australia and now in New Zealand.
Renewal management
Your cover gets reviewed and re-shopped before every renewal, so it keeps up as your life or business changes.
24/7 claims
Lodge a claim any hour, any day. Then your broker manages the insurer for you, start to finish.
Cover for the rest of your world
One broker can look after all of it — just ask.
Business insurance
From cafés and trades to offices, retail and professional services — your broker arranges the cover your business actually needs, then explains it in plain English.
- Public & statutory liability
- Professional indemnity
- Business assets & interruption
- Cyber cover
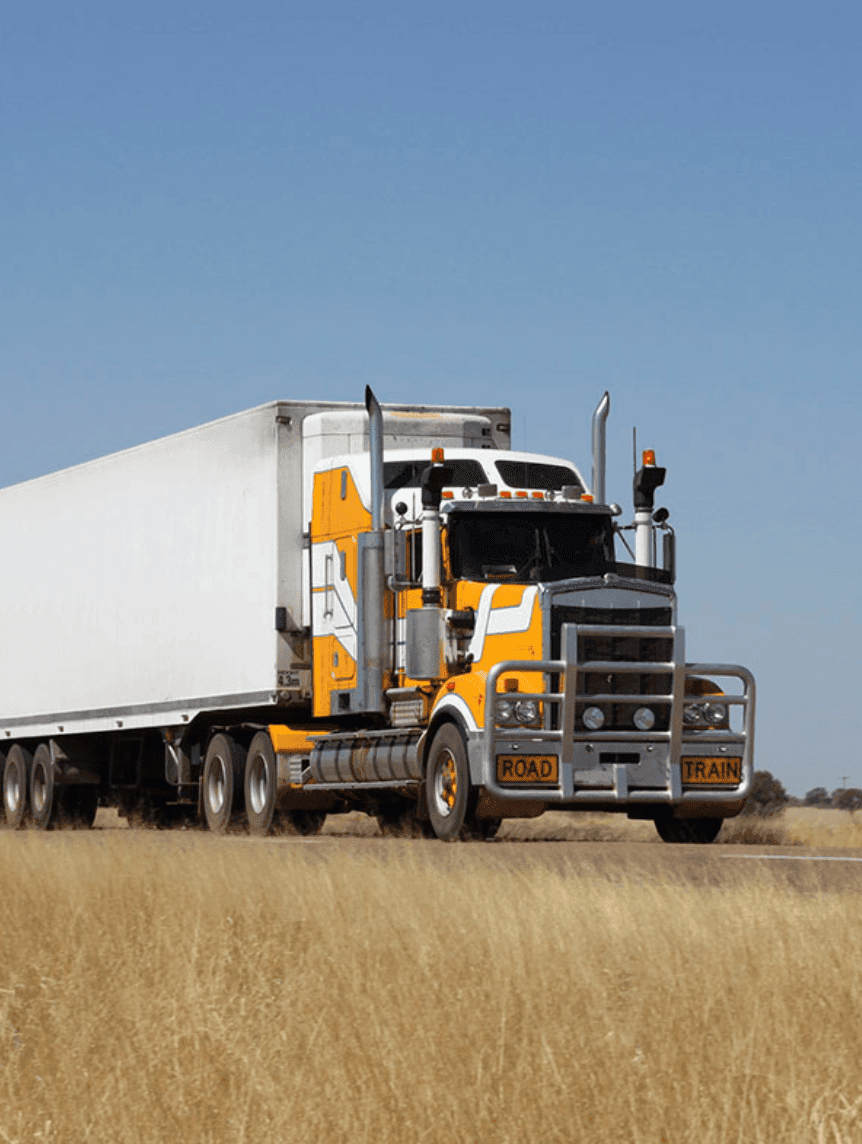
Truck & commercial vehicle
Rigids, tractor units, trailers, utes, vans and whole fleets — cover arranged by brokers who know NZ transport, whether you're line-hauling State Highway 1 or carting stock off-road.
- Trucks, trailers & fleets
- Carriers' liability
- Loss of use cover
- Utes & work vehicles
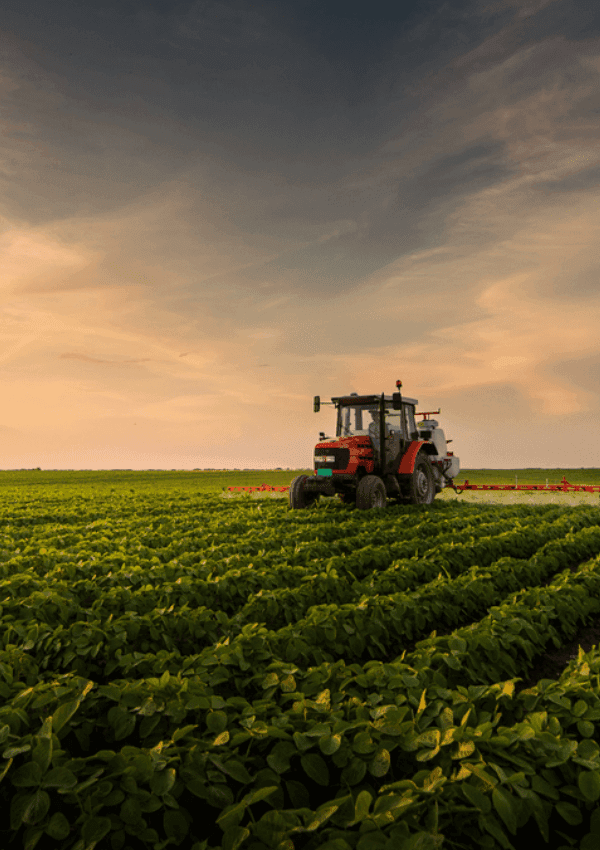
Rural & farm
Farms, lifestyle blocks, machinery, sheds and rural contracting gear — insurance arranged by brokers who understand that a farm is a home, a workplace and a business in one.
- Farm dwellings & sheds
- Tractors & machinery
- Livestock cover
- Farm liability
Home, contents & vehicle
House, contents and private vehicle insurance arranged by a broker — so you get cover that's genuinely right for you, not just the first quote a website spat out.
- House & contents
- Private vehicles
- Boats & trailers
- Landlord cover
Commercial property
Warehouses, retail premises, offices, industrial units and mixed-use buildings — insured for what it would actually cost to rebuild, with cover for the rent you'd lose while that work happens.
- Warehouses, offices & retail
- Loss of rent
- Body corporate & multi-unit
- Landlord liability
Construction & contract works questions, answered straight
No jargon, no fine-print games — just how it actually works.
What does contract works insurance cover?
It responds to physical loss or damage to the work you're building while it's under construction — fire, storm, flooding, vandalism or theft of materials from site are the usual culprits. Policies can often be extended to things like temporary structures, materials in transit and the cost of clearing debris before you rebuild. What's included and what's excluded differs between insurers, so read the wording with your broker rather than assuming.
Single-project or annual — which policy suits me?
It depends on how you work. A single-project policy covers one job for its build period and suits one-off or larger contracts. An annual policy covers the jobs you start during the policy year, usually up to a maximum contract value and build duration, which is often simpler for a builder running several jobs at once. Tell your broker your typical contract size and how many you have on the go, and we'll recommend which fits.
Who arranges contract works — the principal or the contractor?
Either can, and the contract normally spells it out. On some jobs the principal — the owner or developer — insures the works and names the contractors as insured parties; on others the head contractor arranges it. Check the contract before you start and give your broker a copy. The situations that hurt are two policies overlapping, or both parties assuming the other one sorted it.
I'm doing a renovation on an existing building. What changes?
Alterations and extensions sit across two policies: contract works for the new work, and the existing building's policy for the structure you're working on. Insurers commonly want to know before renovation work starts, and some apply conditions or restrictions while a site is active. Talk to your broker — and ask the owner to talk to their insurer — well before work begins, so nobody discovers a gap after the fact.
When does contract works cover end?
Usually at practical completion, or when the works are handed over or put into use — whichever your policy says comes first. Many policies then offer a defects liability or maintenance period extension, which can pick up damage caused while you're back on site fixing defects. The dates and the trigger matter here, so check them with your broker rather than assuming the cover simply runs on.
What do builders usually arrange alongside contract works?
Contract works looks after the job itself; it doesn't cover injury or damage you cause to other people or their property, which is what public liability is for. Plant, tools and equipment cover protects the gear you turn up with, on site and in transit, subject to the security conditions in the policy. Contractors' vehicle cover looks after the utes and trucks. And if you design as well as build, professional indemnity responds to claims arising from that advice. Your broker works out which of these your contracts and your trade actually call for.
Get a quote. It’s free.
One minute now, one friendly phone call later — and the insurance legwork stops being your job.